Uncategorized

Client-Year-End-Planning-Letter-Thumbnail-1280x720.jpg

November 10, 2026

¶1510.5 Sample Year-End Planning Client Letter: Businesses

To the practitioner: For a separate letter on the qualified business income deduction, please see ¶1363.13 Federal Tax Coordinator ¶ H-4326 . For the $26 million gross receipts exception to the prohibition of the cash method for C corporations and certain partnerships see Federal Tax Coordinator ¶ G-2069 . For a separate letter discussing the expanded used of cash basis method of accounting, see ¶1363.14 Federal Tax Coordinator ¶ L-9900 et seq. For a separate letter discussing business property expensing in general, see ¶2165 ¶1240. ¶1248 Federal Tax Coordinator ¶ L-9310 et seq. For a separate letter discussing 100% first-year depreciation, see ¶1249 Federal Tax Coordinator ¶ G-5450 et seq. For the book-tax conformity, see Federal Tax Coordinator ¶ G-2005 . For the preceding year method for determining corporate estimated tax payment, see Federal Tax Coordinator ¶ S-5331 . For a separate letter on corporate estimated tax, see ¶1367 Federal Tax Coordinator ¶ J-7000 et seq. For a separate letter on the tax consequences of debt discharge income, see ¶2248 Federal Tax Coordinator ¶ M-4601 . For the deduction for year-end bonuses, see Federal Tax Coordinator ¶ H-3916 . For a separate letter on passive activity losses, see ¶2265


Dear Business Client:

With year-end approaching, it is time to start thinking about moves that may help lower your business s taxes for this year and next. This year s planning is more challenging than usual due to the uncertainty surrounding pending legislation that could increase corporate tax rates plus the top rates on both business owners ordinary income and capital gain starting next year.

Whether or not tax increases become effective next year, the standard year-end approach of deferring income and accelerating deductions to minimize taxes will continue to produce the best results for most small businesses, as will the bunching of deductible expenses into this year or next to maximize their tax value.

If proposed tax increases do pass, however, the highest income businesses and owners may find that the opposite strategies produce better results: Pulling income into 2021 to be taxed at currently lower rates, and deferring deductible expenses until 2022, when they can be taken to offset what would be higher-taxed income. This will require careful evaluation of all relevant factors.

We have compiled a list of actions based on current tax rules that may help you save tax dollars if you act before year-end. Not all of them will apply to you or your business, but you may benefit from many of them. We can narrow down specific actions when we meet to tailor a particular plan for your business, In the meantime, please review the following list and contact us at your earliest convenience so that we can advise you on which tax-saving moves might be beneficial:


  • Taxpayers other than corporations may be entitled to a deduction of up to 20% of their qualified business income. For 2021, if taxable income exceeds $329,800 for a married couple filing jointly, (about half that for others), the deduction may be limited based on whether the taxpayer is engaged in a service-type trade or business (such as law, accounting, health, or consulting), the amount of W-2 wages paid by the business, and/or the unadjusted basis of qualified property (such as machinery and equipment) held by the business. The limitations are phased in; for example, the phase-in applies to joint filers with taxable income up to $100,000 above the threshold, and to other filers with taxable income up to $50,000 above their threshold.
  • Taxpayers may be able to salvage some or all of this deduction, by deferring income or accelerating deductions to keep income under the dollar thresholds (or be subject to a smaller deduction phaseout) for 2021. Depending on their business model, taxpayers also may be able increase the deduction by increasing W-2 wages before year-end. The rules are quite complex, so don’t make a move in this area without consulting us.
  • More small businesses are able to use the cash (as opposed to accrual) method of accounting than were allowed to do so in earlier years. To qualify as a small business a taxpayer must, among other things, satisfy a gross receipts test, which is satisfied for 2021 if, during a three-year testing period, average annual gross receipts don’t exceed $26 million (next year this dollar amount is estimated to increase to $27 million). Not that many years ago it was $1 million. Cash method taxpayers may find it a lot easier to shift income, for example by holding off billings till next year or by accelerating expenses, for example, paying bills early or by making certain prepayments.
  • Businesses should consider making expenditures that qualify for the liberalized business property expensing option. For tax years beginning in 2021, the expensing limit is $1,050,000, and the investment ceiling limit is $2,620,000. Expensing is generally available for most depreciable property (other than buildings) and off-the-shelf computer software. It is also available for interior improvements to a building (but not for its enlargement), elevators or escalators, or the internal structural framework), for roofs, and for HVAC, fire protection, alarm, and security systems. 2
  • The generous dollar ceilings mean that many small and medium sized businesses that make timely purchases will be able to currently deduct most if not all their outlays for machinery and equipment. What’s more, the expensing deduction is not prorated for the time that the asset is in service during the year. So expensing eligible items acquired and placed in service in the last days of 2021, rather than at the beginning of 2022, can result in a full expensing deduction for 2021.
  • Businesses also can claim a 100% bonus first year depreciation deduction for machinery and equipment bought used (with some exceptions) or new if purchased and placed in service this year, and for qualified improvement property, described above as related to the expensing deduction. The 100% write-off is permitted without any proration based on the length of time that an asset is in service during the tax year. As a result, the 100% bonus first-year write-off is available even if qualifying assets are in service for only a few days in 2021.
  • Businesses may be able to take advantage of the de minimis safe harbor election (also known as the book tax conformity election) to expense the costs of lower-cost assets and materials and supplies, assuming the costs aren’t required to be capitalized under the UNICAP rules. To qualify for the election, the cost of a unit of property can’t exceed $5,000 if the taxpayer has an applicable financial statement (AFS, e.g., a certified audited financial statement along with an independent CPA’s report). If there’s no AFS, the cost of a unit of property can’t exceed $2,500. Where the UNICAP rules aren’t an issue, and where potentially increasing tax rates for 2022 aren’t a concern, consider purchasing qualifying items before the end of 2021.
  • A corporation (other than a large corporation) that anticipates a small net operating loss (NOL) for 2021 (and substantial net income in 2022) may find it worthwhile to accelerate just enough of its 2022 income (or to defer just enough of its 2021 deductions) to create a small amount of net income for 2021. This allows the corporation to base its 2022 estimated tax installments on the relatively small amount of income shown on its 2021 return, rather than having to pay estimated taxes based on 100% of its much larger 2022 taxable income.
  • Year-end bonuses can be timed for maximum tax effect by both cash- and accrual-basis employers. Cash basis employers deduct bonuses in the year paid, so they can time the payment for maximum tax Accrual-basis employers deduct bonuses in the accrual year, when all events related to them are established with reasonable certainty. However, the bonus must be paid within two months after the end of the employer’s tax year for the deduction to be allowed in the earlier accrual year. Accrual employers looking to defer deductions to a higher-taxed future year should consider changing their bonus plans before yearend to set the payment date later than the 2.5-month window or change the bonus plan s terms to make the bonus amount not determinable at yearend.
  • To reduce 2021 taxable income, consider deferring a debt-cancellation event until 2022.
  • Sometimes the disposition of a passive activity can be timed to make best use of its freed-up suspended losses. Where reduction of 2021 income is desired, consider disposing of a passive activity before year-end to take the suspended losses against 2021 income. If possible 2022 top rate increases are a concern, holding off on disposing of the activity until 2022 might save more in future taxes.

These are just some of the year-end steps that can be taken to save taxes. Again, by contacting us, we can tailor a particular plan that will work best for you.

Very truly yours,

© 2021 Thomson Reuters/Tax & Accounting. All Rights Reserved.


time-to-plan.webp

November 10, 2026

¶1510.4 Sample Year-EndPlanning Client Letter: Individuals

To the practitioner: For background information on the 3.8% tax on net investment income of individuals, see Federal Tax Coordinator ¶ A-6360 et seq. For separate letters on the net investment tax, see ¶1369.4 Federal Tax Coordinator ¶ A-6001.2 . For a separate letter discussing the net investment tax and the 0.9% additional Medicare tax on wage and self-employment income, see ¶1369 Federal Tax Coordinator ¶ I-5100 et seq. For an overview of capital gains and losses of individuals, see ¶2256 Federal Tax Coordinator ¶ A-4050 et seq. For a separate letter on the child tax credit, see ¶2397 Federal Tax Coordinator ¶ A-4500 et seq. For the student loan interest deduction, see Federal Tax Coordinator ¶ K-5500 . For For Roth IRAs, see Federal Tax Coordinator ¶ H-12290.1 . For a separate client letter on Roth IRAs, see ¶2331 . For converting a traditional IRA to a Roth IRA, see Federal Tax Coordinator ¶ H-12290.15 . For a separate client letter on Roth IRA rollovers, see ¶2332 . For when income is reported under the cash method of accounting, see Federal Tax Coordinator ¶ G-2411 . For the standard deduction, see Federal Tax Coordinator ¶ A-2800 et seq. For the overall suspension on miscellaneous itemized deductions for 2018-2025, see Federal Tax Coordinator ¶ A-2710 et seq. For a separate letter on the suspension, see ¶2436 Federal Tax Coordinator ¶ K-4001 . For a separate letter on the limitation, see ¶1363.19 Federal Tax Coordinator ¶ M-1600 et seq. For a separate letter on casualty losses, see ¶1265 Federal Tax Coordinator ¶ K-2002 . For a separate letter discussing medical deductions, see ¶1375 Federal Tax Coordinator ¶ K-2800 et seq. For the qualified residence interest, see Federal Tax Coordinator ¶ K-5470 et seq. For a separate letter on the tax consequences of debt discharge income, see ¶2248 Federal Tax Coordinator ¶ K-2002 . For a separate letter discussing medical deductions, see ¶1375 Federal Tax Coordinator ¶ K-2800 et seq. For when payments made by credit card can be deducted, see Federal Tax Coordinator ¶ G-2436 (payment by credit card in general), Federal Tax Coordinator ¶ K-2401 (medical expenses), Federal Tax Coordinator ¶ K-3861 (charitable contributions) (charitable contributions). For the limited itemized deduction for nonbusiness state, local, and foreign taxes, see Federal Tax Coordinator ¶ K-4000 et seq. For a separate client letter on the limitation, see ¶1363.19 Federal Tax Coordinator ¶ H-8275 . For RMDs from IRAs, see Federal Tax Coordinator ¶ H-12264.2 . For separate client letters on RMDs, see ¶1298 , ¶1302 , and ¶1303 . For tax-free IRA qualified charitable distributions (QCDs), see Federal Tax Coordinator ¶ H-12253.2 . For eligible rollover distributions, see Federal Tax Coordinator ¶ H-11400 . For flexible spending accounts (FSAs), see Federal Tax Coordinator ¶ H-2459 . For health savings accounts (HSAs), see Federal Tax Coordinator ¶ H-1350 . For a separate client letter on HSAs, see ¶2184 . For the annual gift tax exclusion, see Federal Tax Coordinator ¶ Q-5002 . For a separate client letter on the annual gift tax exclusion, see ¶1230 . For Income from property given to children subject to the kiddie tax, see Federal Tax Coordinator ¶ A-1308 . For a separate client letter on the kiddie tax, see ¶2375 . For casualty losses, deductible to the extent they’re attributable to a federally declared disaster, see Federal Tax Coordinator ¶ M-1600 et seq. For a separate letter on casualty losses, see ¶1265 . For casualty losses, deductible to the extent they’re attributable to a federally declared disaster, see Federal Tax Coordinator ¶ M-1600 et seq. For a separate letter on casualty losses, see ¶1265 Federal Tax Coordinator ¶ L-4305 et seq.


Dear Client:

With year-end approaching, it is time to start thinking about moves that may help lower your tax bill for this year and next. This year’s planning is more challenging than usual due to the uncertainty surrounding pending legislation that could, among other things, increase top rates on both ordinary income and capital gain starting next year.

Whether or not tax increases become effective next year, the standard year-end approach of deferring income and accelerating deductions to minimize taxes will continue to produce the best results for all but the highest income taxpayers, as will the bunching of deductible expenses into this year or next to avoid restrictions and maximize deductions.

If proposed tax increases do pass, however, the highest income taxpayers may find that the opposite strategies produce better results: Pulling income into 2021 to be taxed at currently lower rates, and deferring deductible expenses until 2022, when they can be taken to offset what would be higher-taxed income. This will require careful evaluation of all relevant factors.

We have compiled a list of actions based on current tax rules that may help you save tax dollars if you act before year-end. Not all of them will apply to you, but you (or a family member) may benefit from many of them. We can narrow down specific actions when we meet to tailor a particular plan for you. In the meantime, please review the following list and contact us at your earliest convenience so that we can advise you on which tax-saving moves might be beneficial:

  • Higher-income individuals must be wary of the 3.8% surtax on certain unearned income. The surtax is 3.8% of the lesser of: (1) net investment income (NII), or (2) the excess of MAGI over a threshold amount ($250,000 for joint filers or surviving spouses, $125,000 for a married individual filing a separate return, and $200,000 in any other case).
  • As year-end nears, the approach taken to minimize or eliminate the 3.8% surtax will depend on the taxpayer s estimated MAGI and NII for the year. Some taxpayers should consider ways to minimize (e.g., through deferral) additional NII for the balance of the year, others should try to reduce MAGI other than NII, and some individuals will need to consider ways to minimize both NII and other types of MAGI. An important exception is that NII does not include distributions from IRAs or most other retirement plans.
  • Pending legislative changes to the 3.8% net investment income tax NIIT proposed to be effective after this tax year would subject high income (e.g., phased-in starting at $500,000 on a joint return; $400,000 for most others) S shareholders, limited partners, and LLC members to NIIT on their pass-through income and gain that is not subject to payroll tax. Accelerating some of this type of income into 2021 could help avoid NIIT on it under the potential 2022 rules, but would also increase 2021 MAGI, potentially exposing other 2021 investment income to the tax.
  • The 0.9% additional Medicare tax also may require higher-income earners to take year-end It applies to individuals whose employment wages and self-employment income total more than an amount equal to the NIIT thresholds, above. Employers must withhold the additional Medicare tax from wages in excess of $200,000 regardless of filing status or other income. Self-employed persons must take it into account in figuring estimated tax. There could be situations where an employee may need to have more withheld toward the end of the year to cover the tax. This would be the case, for example, if an employee earns less than $200,000 from multiple employers but more than that amount in total. Such an employee would owe the additional Medicare tax, but nothing would have been withheld by any employer.
  • Long-term capital gain from sales of assets held for over one year is taxed at 0%, 15% or 20%, depending on the taxpayer’s taxable income. If you hold long-term appreciated-in-value assets, consider selling enough of them to generate long-term capital gains that can be sheltered by the 0% rate. The 0% rate 2 generally applies to net long-term capital gain to the extent that, when added to regular taxable income, it is not more than the maximum zero rate amount (e.g., $80,800 for a married couple; estimated to be $83,350 in 2022). If, say, $5,000 of long-term capital gains you took earlier this year qualifies for the zero rate then try not to sell assets yielding a capital loss before year-end, because the first $5,000 of those losses will offset $5,000 of capital gain that is already tax-free.
  • Postpone income until 2022 and accelerate deductions into 2021 if doing so will enable you to claim larger deductions, credits, and other tax breaks for 2021 that are phased out over varying levels of AGI. These include deductible IRA contributions, child tax credits, higher education tax credits, and deductions for student loan interest. Postponing income also is desirable for taxpayers who anticipate being in a lower tax bracket next year due to changed financial circumstances. Note, however, that in some cases, it may actually pay to accelerate income into 2021. For example, that may be the case for a person who will have a more favorable filing status this year than next (e.g., head of household versus individual filing status), or who expects to be in a higher tax bracket next year. That’s especially a consideration for high income taxpayers who may be subject to higher rates next year under proposed legislation.
  • If you believe a Roth IRA is better for you than a traditional IRA, consider converting traditional-IRA money invested in any beaten-down stocks (or mutual funds) into a Roth IRA in 2021 if eligible to do so. Keep in mind that the conversion will increase your income for 2021, possibly reducing tax breaks subject to phaseout at higher AGI levels. This may be desirable, however, for those potentially subject to higher tax rates under pending legislation.
  • It may be advantageous to try to arrange with your employer to defer, until early 2022, a bonus that may be coming your way. This might cut as well as defer your tax. Again, considerations may be different for the highest income individuals.
  • Many taxpayers won’t want to itemize because of the high basic standard deduction amounts that apply for 2021 ($25,100 for joint filers, $12,550 for singles and for marrieds filing separately, $18,800 for heads of household), and because many itemized deductions have been reduced or abolished, including the $10,000 limit on state and local taxes; miscellaneous itemized deductions; and non-disaster related personal casualty losses. You can still itemize medical expenses that exceed 7.5% of your AGI, state and local taxes up to $10,000, your charitable contributions, plus mortgage interest deductions on a restricted amount of debt, but these deductions won’t save taxes unless they total more than your standard deduction. In addition to the standard deduction, you can claim a $300 deduction ($600 on a joint return) for cash charitable contributions.
  • Some taxpayers may be able to work around these deduction restrictions by applying a bunching strategy to pull or push discretionary medical expenses and charitable contributions into the year where they will do some tax good. For example, a taxpayer who will be able to itemize deductions this year but not next will benefit by making two years’ worth of charitable contributions this year. The COVID-related increase for 2021 in the income-based charitable deduction limit for cash contributions from 60% to 100% of MAGI assists in this bunching strategy.
  • Consider using a credit card to pay deductible expenses before the end of the year. Doing so will increase your 2021 deductions even if you don’t pay your credit card bill until after the end of the year.
  • If you expect to owe state and local income taxes when you file your return next year and you will be itemizing in 2021, consider asking your employer to increase withholding of state and local taxes (or make estimated tax payments of state and local taxes) before year-end to pull the deduction of those taxes into 2021. But this strategy is not good to the extent it causes your 2021 state and local tax payments to exceed $10,000.
  • Required minimum distributions RMDs from an IRA or 401(k) plan (or other employer-sponsored retirement plan) have not been waived for 2021, as they were for 2020. If you were 72 or older in 2020 you must take an RMD during 2021. Those who turn 72 this year have until April 1 of 2022 to take their first RMD but may want to take it by the end of 2021 to avoid having to double up on RMDs next year.
  • If you are age 70 or older by the end of 2021, and especially if you are unable to itemize your deductions, consider making 2021 charitable donations via qualified charitable distributions from your traditional IRAs. These distributions are made directly to charities from your IRAs, and the amount of the contribution is neither included in your gross income nor deductible on Schedule A, Form 1040. However, 3 you are still entitled to claim the entire standard deduction. (The qualified charitable distribution amount is reduced by any deductible contributions to an IRA made for any year in which you were age 70 or older, unless it reduced a previous qualified charitable distribution exclusion.)
  • Take an eligible rollover distribution from a qualified retirement plan before the end of 2021 if you are facing a penalty for underpayment of estimated tax and increasing your wage withholding won’t sufficiently address the problem. Income tax will be withheld from the distribution and will be applied toward the taxes owed for 2021. You can then timely roll over the gross amount of the distribution, i.e., the net amount you received plus the amount of withheld tax, to a traditional IRA. No part of the distribution will be includible in income for 2021, but the withheld tax will be applied pro rata over the full 2021 tax year to reduce previous underpayments of estimated tax.
  • Consider increasing the amount you set aside for next year in your employer’s FSA if you set aside too little for this year and anticipate similar medical costs next year.
  • If you become eligible in December of 2021 to make HSA contributions, you can make a full year’s worth of deductible HSA contributions for 2021.
  • Make gifts sheltered by the annual gift tax exclusion before the end of the year if doing so may save gift and estate taxes. The exclusion applies to gifts of up to $15,000 made in 2021 to each of an unlimited number of individuals. You can’t carry over unused exclusions to another year. These transfers may save family income taxes where income-earning property is given to family members in lower income tax brackets who are not subject to the kiddie tax.
  • If you were in federally declared disaster area, and you suffered uninsured or unreimbursed disaster related losses, keep in mind you can choose to claim them either on the return for the year the loss occurred (in this instance, the 2021 return normally filed next year), or on the return for the prior year (2020), generating a quicker refund.
  • If you were in a federally declared disaster area, you may want to settle an insurance or damage claim in 2021 to maximize your casualty loss deduction this year.

These are just some of the year-end steps that can be taken to save taxes. Again, by contacting us, we can tailor a particular plan that will work best for you.

Very truly yours,

© 2021 Thomson Reuters/Tax & Accounting. All Rights Reserved.


Trump-Accounts-01-1280x1600.webp

January 8, 2026

Today, President Donald J. Trump joined top lawmakers and philanthropists Michael and Susan Dell to celebrate an extraordinary milestone for Trump Accounts: a historic $6.25 billion charitable commitment from the Dells. Trump Accounts are a new, historic savings tool made possible by President Trump’s landmark Working Families Tax Cuts Act.

This landmark gift — one of the largest direct investments ever made in American families — will dramatically accelerate President Trump’s initiative to give every newborn child a head start toward lifelong financial security and the American Dream.

Here’s what you need to know:

  • Trump Accounts will be available to every U.S. citizen born between January 1, 2025, and December 31, 2028. These innovative, tax-advantaged savings accounts — created through President Trump’s Working Families Tax Cuts Act — enable a generation of American children to begin building wealth from the moment they are born.
  • Each Trump Account will launch with a one-time $1,000 government seed contribution. Families and others can contribute up to $5,000 annually; the funds will be invested in a broad stock-market index, remain private property under guardian control until age 18, and, if fully funded and left untouched, could grow to as much as $1.9 million by age 28.
  • Thanks to the Dell’s unprecedented gift, the first 25 million American children age 10 and under living in ZIP codes with median incomes below $150,000 will receive an additional $250. This historic act of generosity will give millions of low- and middle-income children an even stronger shot at achieving the American Dream.

Learn more at trumpaccounts.gov.

Frequently Asked Questions:

  • What is a Trump Account?
    A Trump Account is a tax-deferred savings account for children under 18. The accounts are designed to grow with investment earnings over time, and when the child becomes an adult, the accounts generally function like a traditional IRA.
  • Who is eligible?
    Any child under 18 with a valid Social Security number may open a Trump Account. Parents or guardians must set up and manage the account until the child turns 18.
  • What is the $1,000 government contribution?
    The parent or guardian of a child born between calendar year 2025 and 2028 who is a U.S. citizen with a valid Social Security number may choose to have a one-time $1,000 contribution made by Treasury to the child’s Trump Account. This contribution does not count against the annual $5,000 contribution limit. This benefit is available for these children so long as the account is opened before the year in which the child turns age 18.
  • Do Trump Accounts protect taxpayer dollars by preventing waste, fraud, and abuse?
    Trump Accounts are built with strict safeguards to protect taxpayer funds, including requiring a valid Social Security number and limiting the one-time $1,000 pilot contribution exclusively to U.S. citizens born between calendar years 2025 and 2028, ensuring this benefit goes only to eligible American children.
  • Who can contribute to a Trump Account?
    Children, parents or guardians, grandparents, family members, friends, and employers (with the first $2,500 per employee per year excluded from the employee’s income) may make contributions. Additionally, qualifying charitable organizations and government entities (e.g., states, tribes, localities, etc.) may make contributions for all children in a “qualified class” (e.g., all children born in a year, all children in a state, all children nationwide, etc.).
  • How much can be contributed each year?
    The annual contribution limit is $5,000 total per child, with cost-of-living increases after 2027. Qualifying charitable organizations and government entities may make additional contributions that do not count toward the $5,000 limit.
  • When do contributions begin?
    Contributions to Trump Accounts will be accepted starting July 4, 2026.
  • How are Trump Accounts invested?
    By law, Trump Accounts may only be invested in broad U.S. equity index funds that track the overall U.S. stock market (e.g., S&P 500), do not use leverage, and charge no more than 0.10% in annual fees.
  • Can money be withdrawn before age 18?
    No. Funds may not be withdrawn before the child turns 18, except for a rollover of the entire account to a Trump Account with another brokerage (trustee-to-trustee transfer), certain rollovers to an ABLE account in the year the child turns 17, or distribution upon death. After age 18, standard IRA rules for withdrawals apply.
  • What happens when the child turns 18?
    At age 18, the account is generally treated like a traditional IRA. The account holder may continue contributing subject to IRA rules and earned income requirements. Withdrawals follow traditional IRA rules and the account holder may be subject to a 10% additional tax for any withdrawal before age 59 ½, unless an exception (such as for distributions for higher education expenses or first home purchases) applies.
  • How do I open a Trump Account for my child?
    Use IRS Form 4547 to make the election to establish an initial Trump Account for the exclusive benefit of a child who is eligible; also use Form 4547 to make an election for the $1,000 pilot program contribution from the U.S. Treasury to the child’s Trump Account if they are eligible for the contribution. After the election is made, beginning in May 2026, Treasury or its agent will send information to the individual who made the election to activate the account through an authentication process and complete the opening of the initial Trump account.
  • When can I open a Trump Account for my child?
    IRS Form 4547 can be filed at any time, including at the same time as the electing individual’s 2025 income tax return is filed. Beginning mid-2026, these elections can also be made through an online account at trumpaccounts.gov.
  • Where will the Trump Account be held? Can I use my preferred brokerage firm?
    All Trump Accounts will initially be created and held with Treasury’s designated financial agent. At a later date, parents or guardians will be able to transfer the full balance of a Trump Account to their preferred brokerage firm through a simple trustee-to-trustee rollover.
  • Can my employer offer Trump Account contributions through a cafeteria plan?
    Yes. Pre-tax salary-reduction contributions will be allowed to Trump Accounts owned by an employee’s dependent child through an employer-sponsored cafeteria plan, up to $2,500 per employee per year.

overtime-shutterstock_472877095-e1752181075641.jpg

July 10, 2025

Key Provisions of the “No Tax on Overtime” Rule:

  1. Effective Date: The new rule is retroactive to January 1, 2025, and is set to expire on December 31, 2028.
  2. Nature of the Benefit: This is a federal income tax deduction, not a complete exemption from all taxes on overtime. It allows eligible employees to deduct a portion of their qualified overtime earnings from their federal taxable income when they file their annual tax return.
  3. Eligibility:
    • Applies to non-exempt employees who receive overtime compensation as required by Section 7 of the Fair Labor Standards Act (FLSA).
    • There are income limitations: The deduction begins to phase out for individuals with a modified adjusted gross income (MAGI) exceeding $150,000 (or $300,000 for those filing jointly). Highly compensated employees are generally not eligible.
  4. Deduction Limit: Eligible employees can deduct up to $12,500 of qualified overtime compensation per year (or $25,000 for those filing jointly). This is an “above-the-line” deduction, meaning it can be claimed even if the employee does not itemize deductions.
  5. What Qualifies: Only overtime compensation that is required under the FLSA and is in excess of the regular rate qualifies for this deduction. Overtime premiums paid under state laws or collective bargaining agreements that are not FLSA-required generally do not qualify.

How Employers Treat Overtime for Withholding:

This is the most critical aspect for employers. Despite the new deduction for employees, employers’ immediate withholding obligations remain largely unchanged for now.

  1. Continued Withholding of Federal Income Tax: Employers are still required to withhold federal income tax from all overtime wages earned by employees. The employee’s deduction occurs when they file their personal income tax return (Form 1040), not at the time of each paycheck.
  2. Continued Withholding of FICA Taxes: Overtime wages remain fully subject to Social Security and Medicare (FICA) taxes. Employers must continue to withhold and remit these taxes as normal.
  3. State and Local Taxes: The “No Tax on Overtime” provision applies only to federal income tax. State and local income tax treatment of overtime is not affected by this federal law and will vary based on individual state and local regulations.
  4. No Immediate Changes to Payroll Systems/W-4s (for 2025):
    • For the 2025 tax year, employers are not required to immediately change how they calculate or withhold federal income tax on qualifying overtime compensation.
    • Employers may continue to use current IRS withholding tables.
    • No changes to employee W-4 forms are required solely due to this new deduction.
    • The IRS is expected to issue updated withholding guidance and forms, likely by late 2025, with mandatory implementation starting in 2026.
  5. New Reporting Requirements (Form W-2):
    • Employers must report the total amount of “qualified overtime compensation” as a separate line item on employees’ Forms W-2 for year-end reporting.
    • For the 2025 tax year, the Act allows employers to approximate this amount using any “reasonable method” that will be specified by the Treasury Secretary (awaiting further guidance).
  6. Employer Preparation:
    • Accurate Tracking: Ensure robust and clear tracking of regular hours, overtime hours, and the specific portion of overtime that qualifies as “excess of the regular rate” under FLSA.
    • Payroll System Review: Coordinate with payroll providers and software vendors to prepare for necessary system updates to comply with the new W-2 reporting requirements.
    • Employee Communication: Be prepared to answer employee questions about this new deduction, clarifying that while they can claim the deduction on their tax return, employers must still withhold taxes from their paychecks as usual.
    • Monitor IRS Guidance: Stay informed about forthcoming guidance from the IRS and Treasury Department regarding updated withholding tables and specific methods for reporting qualified overtime for 2025 and beyond.

360_F_336524155_1F08VntPM1ORioioXl7AviMvirwWAuZ2-e1752181135370.jpg

July 7, 2025

Below are details of many of the tax provisions in the One Big Beautiful Bill Act, which was signed into law Friday by President Donald Trump.

The House approved the measure Thursday in a 218-214 vote, after the Senate approved it Tuesday by a 51-50 vote, with Vice President JD Vance casting the tie-breaking vote.

The bill extends many of the expiring provisions from the Tax Cuts and Jobs Act (TCJA), P.L. 115-97. It also addresses other tax priorities of the Trump administration, including providing deductions to eliminate income taxes on certain tips and overtime pay.

The bill also revamps some of the TCJA’s provisions on the taxation of corporations’ foreign income and terminates a large number of clean energy tax incentives.

In a statement, AICPA President and CEO Mark Koziel, CPA, CGMA, called the bill “a win for millions of businesses, taxpayers, and tax practitioners across the country.”

Additionally, Koziel said in the statement: “No bill is perfect — however, there are many beneficial tax provisions in this bill that I believe support the business community and will help grow our economy. The tax provisions in this bill will help facilitate tax planning earlier in the year, which can help reduce the anxiety of the unknown for many taxpayers.”

The AICPA has published charts comparing tax and personal financial planning provisions of the bill with current law (free site registration required).

Provisions for individuals

Tax rates: The bill generally makes the tax rates enacted in 2017 in the TCJA permanent. The bill adds an additional year of inflation adjustment for determining the dollar amounts at which any rate bracket higher than 12% ends and at which any rate bracket higher than 22% begins.

Standard deduction: The bill makes the TCJA’s increased standard deduction amounts permanent. For tax years beginning after 2024, the standard deduction increases to $15,750 for single filers, $23,625 for heads of household, and $31,500 for married individuals filing jointly. The standard deduction will be adjusted for inflation after that. These changes have been made retroactive to include 2025.

SALT cap: The bill temporarily increases the limit on the federal deduction for state and local taxes (the SALT cap) to $40,000 (from the current $10,000) and adjusts it for inflation. In 2026, the cap will be $40,400, and then will increase by 1% annually, through 2029. Starting in 2030, it will revert to the current $10,000.

The amount of the deduction available to a taxpayer phases down for taxpayers with modified adjusted gross income (MAGI) over $500,000 (in 2025). The MAGI threshold will be adjusted for inflation through 2029. The phasedown will reduce the taxpayer’s SALT deduction by 30% of the amount the taxpayer’s MAGI exceeded the threshold, but the limit on a taxpayer’s SALT deduction could never go below $10,000.

The version of the bill that passed the House in May also increased the SALT cap to $40,000, but included provisions to limit taxpayers’ attempt to circumvent the cap, including not allowing specified service trades or businesses (SSTBs) to deduct state and local income taxes. This provision would limit the usefulness of state passthrough entity taxes (PTETs) in avoiding the SALT cap. The Senate Finance Committee’s version of the bill took a different tack and would have limited all passthrough entity owners’ PTET SALT deduction to the unused portion of their SALT deduction plus the greater of $40,000 of their allocation of the PTET or 50% of their allocation of the PTET.

The adopted version of the bill merely increases the SALT cap and does not attempt to limit or address the various workarounds that taxpayers are currently using to avoid the SALT cap. The AICPA had advocated against limiting the use of PTETs.

In the AICPA statement, Koziel said: “We are thankful to the members of Congress who supported millions of businesses’ ability to retain pass-through entity tax SALT deduction and our partners throughout the state CPA societies and other professional service businesses for their diligent advocacy on this important issue.” (For more on this, see “Senate Budget Bill Would Preserve PTET SALT Deduction.”)

Personal exemptions and senior deduction: The Senate bill permanently sets the deduction for personal exemptions at zero. However, it provides a temporary $6,000 deduction under Sec. 151 for individual taxpayers who are age 65 or older. This senior deduction begins to phase out when a taxpayer’s MAGI exceeds $75,000 ($150,000 in the case of a joint return). It will be in effect for the years 2025 through 2028.

Child tax credit: The bill increases the amount of the nonrefundable child tax credit to $2,200 per child beginning in 2025 and indexes the credit amount for inflation. The bill also makes permanent the $1,400 refundable child tax credit, adjusted for inflation. It in addition makes permanent the increased income phaseout threshold amounts of $200,000 ($400,000 in the case of a joint return), as well as the $500 nonrefundable credit for each dependent of the taxpayer other than a qualifying child.

QBI deduction: The bill makes the Sec. 199A qualified business income (QBI) deduction permanent and keeps the deduction rate at 20% (the bill passed by the House would have raised it to 23%). The bill expands the Sec. 199A deduction limit phase-in range for SSTBs and other entities subject to the wage and investment limitation by increasing the $50,000 amount for non-joint returns to $75,000 and the $100,000 amount for joint returns to $150,000.

The bill also introduces an inflation-adjusted minimum deduction of $400 for taxpayers who have at least $1,000 of QBI from one or more active trades or businesses in which they materially participate.

Estate and gift tax exemption amounts: The bill amends Sec. 2010 to permanently increase the estate tax exemption and lifetime gift tax exemption amounts to $15 million for single filers ($30 million for married filing jointly) in 2026 and index the exemption amount for inflation after that.

Alternative minimum tax exemption: The bill permanently extends the TCJA’s increased individual alternative minimum tax (AMT) exemption amounts and reverts the exemption phaseout thresholds to their 2018 levels of $500,000 ($1 million in the case of a joint return), indexed for inflation. However, in a change from the Senate Finance Committee’s version of the bill, the bill increases the phaseout of the exemption amount from 25% to 50% of the amount by which the taxpayer’s alternative minimum taxable income exceeds the threshold amount.

Mortgage interest deduction: The bill permanently extends the TCJA’s provision limiting the Sec. 163 qualified residence interest deduction to the first $750,000 in home mortgage acquisition debt. It also makes permanent the exclusion of interest on home-equity indebtedness from the definition of qualified residence interest. The bill also treats certain mortgage insurance premiums on acquisition indebtedness as qualified residence interest.

Casualty loss deductions: Under the bill, the TCJA’s provision limiting the itemized deduction for personal casualty losses to losses resulting from federally declared disasters becomes permanent, but the bill expands the provision to include certain state-declared disasters.

A letter to four Senate leaders dated June 28 reiterated the AICPA’s appreciation for multiple provisions in the bill and noted the AICPA’s “continued concern” regarding the permanency of the TCJA limitation on such deductions.

“We hope to continue to work with you to find improvements on this issue in any future tax legislation,” the letter said. “That being said, on balance, the legislation that the Senate will consider makes significant improvements to the OBBB that truly promote business growth. With that in mind, we express our strong support for the Senate tax provisions and urge their inclusion in any final version of the OBBB that becomes law.”

Miscellaneous itemized deductions: The bill makes permanent the TCJA’s suspension of the Sec. 67(g) deduction for miscellaneous itemized deductions but removes unreimbursed employee expenses for eligible educators from the list of miscellaneous itemized deductions.

Itemized deductions limitation: The bill permanently removes the Sec. 68 overall limitation on itemized deductions (known as the Pease limitation) and replaces it with a new overall limitation on the tax benefit of itemized deductions. The amount of itemized deductions otherwise allowable would be reduced by 2/37 of the lesser of (1) the amount of the itemized deductions or (2) the amount of the taxpayer’s taxable income that exceeds the start of the 37% tax rate bracket.

Bicycle commuting reimbursements: The bill permanently excludes qualified bicycle commuting reimbursements from the list of qualified transportation fringe and other commuting benefits, making them taxable to employees.

Moving expense deduction: The bill permanently eliminates the Sec. 217 deduction for moving expenses, except for members of the armed forces and certain members of the intelligence community.

Wagering losses: The bill amends Sec. 165(d) to clarify that the term “losses from wagering transactions” includes any deduction otherwise allowable under Chapter 1 of the Code incurred in carrying on any wagering transactions. The bill limits the term “losses from wagering transactions” to 90% of the amount of those losses, and losses will be deductible only to the extent of the taxpayer’s gains from wagering transactions during the tax year.

ABLE accounts: The bill makes various changes to Sec. 529A ABLE accounts, including making permanent the TJCA’s increased limitation on contributions to ABLE accounts. The bill also makes permanent the inclusion of ABLE account contributions as eligible Sec. 25B saver’s credit contributions, but after 2026 only ABLE account contributions will be eligible saver’s credit contributions. The credit amount increases from $2,000 to $2,100. (This increase was not included in the Senate Finance Committee’s version of the bill.)

Student loan debt discharge: The bill makes permanent and makes some adjustments to the Sec. 108(f)(5) provision excluding from gross income student loans that are discharged on account of death or disability. The bill also requires the inclusion of the taxpayer’s Social Security number (SSN) on the relevant income tax return when a student loan is discharged.

No tax on tips: The bill provides a temporary deduction of up to $25,000 for qualified tips received by an individual in an occupation that customarily and regularly receives tips. The deduction will be allowed for both employees receiving a Form W-2, Wage and Tax Statement, and independent contractors who receive Form 1099-K, Payment Card and Third Party Network Transactions, or Form 1099-NEC, Nonemployee Compensation, or who report tips on Form 4317, Social Security and Medicare Tax on Unreported Tip Income. The deduction would be an above-the-line deduction and, therefore, available for taxpayers who claim the standard deduction or itemize deductions. The deduction begins to phase out when the taxpayer’s MAGI exceeds $150,000 ($300,000 in the case of a joint return). This temporary deduction will be available for tax years 2025 through 2028. A transition rule will allow employers required to furnish statements enumerating an individual’s tips for tax year 2025 to use “any reasonable method” to estimate designated tip amounts.

The bill also extends the Sec. 45B credit for a portion of employer Social Security taxes paid with respect to employee cash tips to certain beauty service businesses.

No tax on overtime: The bill provides a temporary above-the-line deduction of up to $12,500 ($25,000 in the case of a joint return) for qualified overtime compensation received by an individual during a given tax year. The deduction begins to phase out when the taxpayer’s MAGI exceeds $150,000 ($300,000 in the case of a joint return). The bill defines qualified overtime compensation as overtime compensation paid to an individual required under Section 7 of the Fair Labor Standards Act of 1938 that is in excess of the regular rate (as used in that section) at which the individual is employed. Overtime deductions would only be allowed for qualified overtime compensation if the total amount of qualified overtime compensation is reported separately on Form W-2 (or Form 1099, if the worker is not an employee). This temporary deduction will be available for tax years 2025 through 2028.

Car loan interest: For the years 2025 through 2028, the bill excludes qualified passenger vehicle loan interest from the definition of personal interest in Sec. 163(h). Qualified passenger vehicle loan interest is defined as interest paid or accrued during tax year on indebtedness incurred by the taxpayer after Dec. 31, 2024, for the purchase of, and that is secured by a first lien on, an applicable passenger vehicle for personal use. Among other restrictions, applicable passenger vehicles must have had their final assembly in the United States.

The exclusion is capped at $10,000 per year and will phase out for taxpayers with MAGI in excess of $100,000 ($200,000 for married taxpayers filing jointly).

Adoption credit: The bill makes a portion (up to $5,000) of the Sec. 23 adoption credit refundable. That amount will be adjusted for inflation.

Dependent care assistance programs: The maximum annual amount excludable from income under a Sec. 129 dependent care assistance program increases from $5,000 to $7,500 under the bill.

Child and dependent care credit: The bill permanently increases the amount of the child and dependent care tax credit from 35% to 50% of qualifying expenses. The credit rate phases down for taxpayers with adjusted gross income (AGI) over $15,000. It will be reduced by 1 percentage point (but not below 35%) for each $2,000 that the taxpayer’s AGI exceeds $15,000. It will then be further reduced by (but not below 20%) 1 percentage point for each $2,000 ($4,000 for joint returns) that their AGI exceeds $75,000 ($150,000 for joint returns).

Trump accounts: The Senate version of the bill takes the House bill’s concept of tax-free savings accounts for minors, called Trump accounts, and revises it to make them a form of individual retirement account (IRA) under Sec. 408(a). Under the bill, Trump accounts will be IRAs (but not Roth IRAs) for the exclusive benefit of individuals under 18. Contributions can only be made in calendar years before the beneficiary turns 18 and distributions can only be made starting in the calendar year the beneficiary turns 18. Trump accounts will have to be designated as such when they are set up, and the bill does not allow Trump account contributions until 12 months after the date of enactment of the bill.

Under the bill, Treasury can set up Trump accounts for individuals that it identifies as eligible and for which no Trump account has already been created.

Eligible investments in Trump accounts would generally be mutual funds and indexed ETFs. Contributions (other than qualified rollover contributions) will be capped at $5,000 a year (adjusted for inflation after 2027). State, local, and tribal governments and charitable organizations could make “general funding contributions,” which would be contributions made to a specified qualified class of Trump account beneficiaries. Qualified classes include beneficiaries under the age of 18, and the general funding contribution can specify geographical areas or specific birth years of beneficiaries whose accounts will receive the contributions.

The bill creates a new Sec. 128 that allows for employer contributions to Trump accounts. These contributions will not be included in the employee’s income.

A new Sec. 6434 creates a Trump accounts contribution pilot program that provides a $1,000 tax credit for opening a Trump account for a child born between Jan. 1, 2025, and Dec. 31, 2028. The bill appropriates $410 million, to remain available through Sept. 30, 2034, to fund Trump accounts.

Credit for contributions to scholarship-granting organizations: The bill enacts a new Sec. 25F that provides a credit of the greater of $5,000 or 10% of the taxpayer’s AGI for charitable contributions to scholarship-granting organizations. The credit comes with a $4 billion annual cap (starting in 2027), and the credit will be allocated on a first-come, first-served basis, up to that cap.

The provision also creates a Sec. 139K, which excludes from income scholarships for the qualified secondary or elementary education expenses of eligible students.

Sec. 529 plans: The bill allows tax-exempt distributions from Sec. 529 savings plans to be used for additional educational expenses in connection with enrollment or attendance at an elementary or secondary school. The bill also allows tax-exempt distributions from 529 savings plans to be used for additional qualified higher education expenses, including “qualified postsecondary credentialing expenses.”

Charitable contribution deduction: The bill creates a charitable contribution deduction for taxpayers who do not elect to itemize, allowing nonitemizers to claim a deduction of up to $1,000 for single filers or $2,000 for married taxpayers filing jointly for certain charitable contributions. For itemizers, the bill imposes a 0.5% floor on the charitable contribution deduction: The amount of an individual’s charitable contributions for a tax year is reduced by 0.5% of the taxpayer’s contribution base for the tax year. For corporations, the floor will be 1% of the corporation’s taxable income, and the charitable contribution deduction cannot exceed the current 10%-of-taxable-income limit.

Business provisions

Bonus depreciation: The bill permanently extends the Sec. 168 additional first-year (bonus) depreciation deduction. The allowance is increased to 100% for property acquired and placed in service on or after Jan. 19, 2025, as well as for specified plants planted or grafted on or after Jan. 19, 2025.

Sec. 179 expensing: The bill increases the maximum amount a taxpayer may expense under Sec. 179 to $2.5 million, reduced by the amount by which the cost of qualifying property exceeds $4 million.

Research-and-development expenses: The bill allows taxpayers to immediately deduct domestic research or experimental expenditures paid or incurred in tax years beginning after Dec. 31, 2024. However, research or experimental expenditures attributable to research that is conducted outside the United States will continue to be required to be capitalized and amortized over 15 years under Sec. 174.

Small business taxpayers with average annual gross receipts of $31 million or less will generally be permitted to apply this change retroactively to tax years beginning after Dec. 31, 2021. And all taxpayers that made domestic research or experimental expenditures after Dec. 31, 2021, and before Jan. 1, 2025, will be permitted to elect to accelerate the remaining deductions for those expenditures over a one- or two-year period.

Limitation on business interest: The bill reinstates the EBITDA limitation under Sec. 163(j) for tax years beginning after Dec. 31, 2024. Therefore, for purposes of the Sec. 163(j) interest deduction limitation for these years, adjusted taxable income would be computed without regard to the deduction for depreciation, amortization, or depletion. The bill would also modify the definition of “motor vehicle” to allow interest on floor plan financing for certain trailers and campers to be deductible.

Paid family and medical leave credit: Under the bill, Sec. 45S is amended to make the employer credit for paid family and medical leave permanent.

Special depreciation allowance for qualified production property: The bill allows an additional first-year depreciation deduction equal to 100% of the adjusted basis of “qualified production property.” Qualified production property is generally nonresidential real property used in manufacturing.

Advanced manufacturing investment credit: Under the bill, the advanced manufacturing investment credit rate increases from 25% to 35%, effective for property placed in service after Dec. 31, 2025. (The Senate Finance Committee version of the bill had proposed increasing the rate to 30%.)

Spaceports: The bill amends Sec. 142(a)(1) to ensure spaceports are treated like airports under the exempt-facility bond rules. A spaceport is defined as a facility close to a launch or reentry site that is used to manufacture, assemble, or repair spacecraft or space cargo or is used for flight control operations, to provide launch or reentry services, or to transfer crew, spaceflight participants, or space cargo to or from a spacecraft. This is a new provision that was not in the Senate Finance Committee’s version of the bill.

Employer-provided child care credit: The bill increases the amount of qualified child care expenses taken into account for purposes of the Sec. 45F employer-provided child care credit from 25% to 40%. The maximum amount of the credit increases from $150,000 to $500,000 ($600,000 for eligible small businesses) and will be adjusted for inflation.

Opportunity zones: The bill makes opportunity zones permanent but with several changes, including narrowing the definition of “low-income community.” The changes would generally take effect Jan. 1, 2027.

New markets tax credit: The bill makes the Sec. 45D new markets tax credit permanent.

Percentage-of-completion method: The bill provides an exception to the Sec. 460(e) requirement to use the percentage-of-completion accounting method for certain residential construction contracts entered into after the date of the bill’s enactment.

Qualified small business stock: The bill increases the Sec. 1202 exclusion for gain from qualified small business stock. For qualified small business stock acquired after the date of enactment of the bill and held for at least four years, the percentage of gain excluded from gross income will rise from 50% to 75%. If it is held for five years or more, the exclusion percentage will go up to 100%.

Excess business losses: The bill makes Sec. 461(l)(1) limitation on excess business losses of noncorporate taxpayers permanent. It was scheduled to expire after 2028. Language in the Senate Finance Committee version of the bill would have treated carried over excess business losses as excess business losses, and therefore subject to the Sec. 461(l) limitation, rather than as net operating losses (NOLs), which are not subject to Sec. 461(l). That language was dropped from the final bill.

Clean energy incentives

The bill terminates a large number of clean energy tax incentives:

    • Sec. 25E previously owned clean vehicle credit (terminates after Sept. 30, 2025);
    • Sec. 30D clean vehicle credit (terminates for vehicles acquired after Sept. 30, 2025);
    • Sec. 45W qualified commercial clean vehicle credit (terminates after Sept. 30, 2025);
    • Sec. 30C alternative fuel vehicle refueling credit (terminates after June 30, 2026);
    • Sec. 25C energy-efficient home improvement credit (terminates after Dec. 31, 2025);
    • Sec. 25D residential clean energy credit (terminates for expenditures made after Dec. 31, 2025);
    • Sec. 179D energy-efficient commercial buildings deduction (terminates for property the construction of which begins after June 30, 2026);
    • Sec. 45L new energy-efficient home credit (terminates after June 30, 2026);
    • Sec. 45V clean hydrogen production credit (terminates after Jan. 1, 2028); and
    • Sec. 6426(k) sustainable aviation fuel credit (terminates after Sept. 30, 2025).

The Sec. 168(e)(3)(B)(vi) provision allowing cost recovery for certain energy property and qualified clean energy facilities, property, and technology will be terminated after Dec. 31, 2025, for energy property and after the date of enactment for qualified clean energy facilities, property, and technology.

The bill places restrictions on claiming the Sec. 45U nuclear power production credit for foreign entities and for facilities that use imported nuclear fuel.

The Sec. 45Y clean electricity production credit is terminated for wind and solar facilities placed in service after Dec. 31, 2027. No credit will be allowed to facilities that are owned or controlled by certain foreign entities. The Sec. 48E clean electricity investment credit is also terminated for wind and solar facilities placed in service after Dec. 31, 2027. Restrictions are also placed around claims by facilities owned or controlled by certain foreign entities.

The Sec. 45Z clean fuel production credit is extended through 2029, and prohibitions are placed on the use of foreign feedstocks.

International provisions

Foreign tax credit limitation: The Senate Finance Committee version of the bill would have limited the deductions of a U.S. shareholder allocable to income in the global intangible low-tax income (GILTI) category when determining its foreign tax credit limitation. It would also have modified the determination of deemed paid credit for taxes properly attributable to tested income and change the rules for sourcing certain income from the sale of inventory produced in the United States. The adopted bill revises that provision and treats those deductions as allocable to “net CFC tested income” (which is what the bill turns GILTI into, see below).

Deemed paid credit: The bill amends Sec. 960(d)(1) to increase the deemed paid credit for Subpart F inclusions from 80% to 90%.

GILTI and FDII: The bill decreases the Sec. 250 deduction percentage for tax years beginning after Dec. 31, 2025, to 33.34% for foreign-derived intangible income (FDII) and 40% for GILTI, resulting in an effective tax rate of 14% for both FDII and GILTI. The bill also proposes changing the definition of deduction-eligible income for purposes of determining FDII. The bill also eliminates the use of a corporation’s deemed tangible income return for determining FDII and the use of net deemed tangible income return in determining GILTI. These changes result in the elimination of the terms FDII and GILTI, which will be renamed “foreign-derived deduction eligible income” and “net CFC tested income,” respectively.

BEAT: The bill increases the base-erosion and anti-abuse tax (BEAT) rate from 10% to 10.5% (the Senate Finance Committee version would have increased it to 14%). Other BEAT changes that were included in the Senate Finance Committee version have been eliminated.

Business interest limitation: The bill provides that the Sec. 163(j) business interest limitation will be calculated prior to the application of any interest capitalization provision.

Remedies against unfair foreign taxes: The provision of the Senate Finance Committee version of the bill that would have enacted a new Sec. 899 to impose increased rates of tax (up to 15%) on certain affected taxpayers connected to countries that are deemed to impose unfair foreign taxes was dropped from the final bill.

Administrative provisions and excise taxes

Third-party network transaction reporting threshold: The bill reverts to the prior rule for Form 1099-K reporting, under which a third-party settlement organization is required to report, unless the aggregate value of third-party network transactions with respect to a participating payee for the year exceeds $20,000 and the aggregate number of such transactions with respect to a participating payee exceeds 200. The threshold had been phasing down and was scheduled to be $600 starting next year.

Form 1099 reporting threshold: The bill increases the information-reporting threshold for certain payments to persons engaged in a trade or business and payments of remuneration for services to $2,000 in a calendar year (from $600), with the threshold amount to be indexed annually for inflation in calendar years after 2026.

Firearms transfer tax: The bill reduces the Sec. 5811 transfer tax on certain firearms.

Farmland sales: The bill adds a new Sec. 1062 that allows income tax resulting from the sale of farmland to a qualified farmer to be paid in four annual installments. This is a new provision.

Litigation financing: The bill as originally considered would have imposed a 31.8% tax on “qualified litigation proceeds” received by a “covered party,” as defined in the bill. That provision was dropped from the final bill.

Remittance transfer tax: The bill imposes a 1% tax on “remittance transfers,” imposed on the sender. A remittance transfer for these purposes is a transfer of cash, a money order, a cashier’s check, or similar physical instrument. It does not include funds withdrawn from an account held with a financial institution or charged to a credit or debit card.

Under Section 919(g) of the Electronic Fund Transfer Act, a remittance transfer is an electronic transfer of funds requested by a sender to a designated recipient that is initiated by a remittance transfer provider. A remittance transfer provider is any person or financial institution that provides remittance transfers for consumers in the normal course of its business, whether or not the consumer holds an account with the financial institution.

The Senate Finance Committee version of the bill would have imposed a 3.5% tax on such transfers.

Employee retention credit enforcement: The bill requires employee retention credit (ERC) promoters to comply with due diligence requirements with respect to a taxpayer’s eligibility for (or the amount of) an ERC. The bill applies a $1,000 penalty for each failure to comply. It also extends the penalty for excessive refund claims to employment tax refund claims. It also prevents the IRS from issuing any additional unpaid claims under Sec. 3134, unless a claim for a credit or refund was filed on or before Jan. 31, 2024.

SSN requirements: The bill imposes an SSN requirement for claiming an American opportunity or lifetime learning credit under Sec. 25A.

EITC program: The Senate Finance Committee version of the bill proposed creating an earned income tax credit (EITC) certification program to allow the IRS to detect and manage duplicative EITC claims. That proposal was dropped from the bill.

Penalties for unauthorized disclosure of taxpayer information: A proposal in the Senate Finance Committee version of the bill to increase the Sec. 7213 penalties for unauthorized disclosure of taxpayer information was also removed.

— Alistair M. Nevius, J.D., is a freelance writer in North Carolina. To comment on this article or to suggest an idea for another article, contact Neil Amato at Neil.Amato@aicpa-cima.com.

0503-Abbott-Voucher-Signing-BD-TT-1291.webp

June 30, 2025

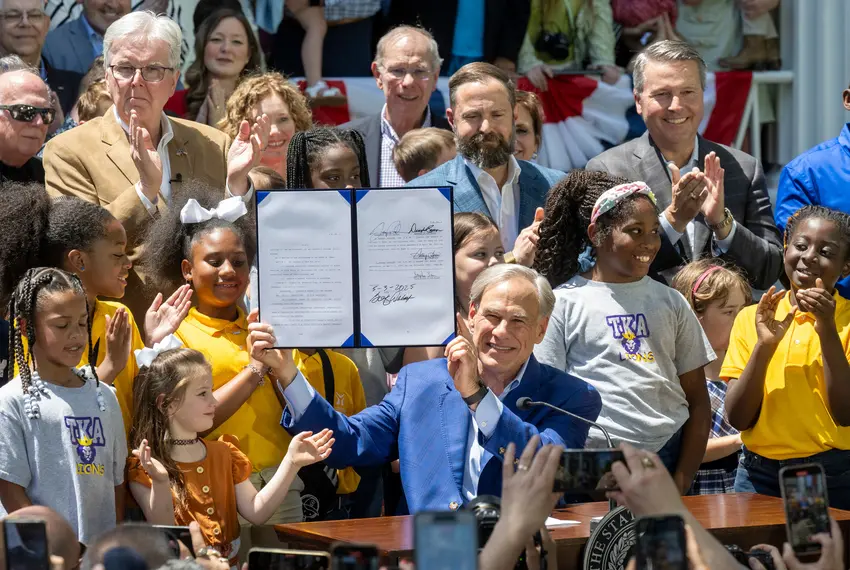
Texas will give participating families about $10,000 to pay for their kids’ private schooling. Other details about the program, set to launch in 2026, are unclear.

The law will go into effect on Sept. 1, with the program expected to launch in late 2026.

Families can receive about $10,000 to send their children to private school on taxpayers’ dime

Texas will spend $1 billion on vouchers in the first two years, but costs could skyrocket

Most families can participate, including some of the wealthiest Texans

The program launches next year, but other specifics are still unclear

Participating students won’t have to take the STAAR test

Contributor

Jaden Edison is the public education reporter for The Texas Tribune. He previously reported on justice for The Connecticut Mirror and interned at Poynter. He holds master’s and bachelor’s degrees from Columbia University and Texas State University, respectively. While at Texas State, he was editor-in-chief of The University Star.

You can reach him at jaden.edison@texastribune.org or on X @edisonjaden.